The premium renews. The customer doesn't have to.
Every year, one in three insurance customers actively shops a renewal. Every year, comparison sites capture more of the first click. GoSales Solutions is the compliant, data-led partner that wins back the second click — across motor, home, health, life and commercial lines in Ireland, the UK, and priority EU markets.
THE MARKET, IN MOTION
Three markets. One acquisition clock.
Motor renewal. Home switching. Life protection. Health cover. Commercial and small-business lines. Five products, three regulatory regimes, one commercial truth: insurance acquisition is won in the thirty days before renewal — or lost for another twelve months.
IRELAND
€18.1B
Total Irish insurance premium across life and non-life markets.
INSURANCE IRELAND · 2024
UNITED KINGDOM
36%
Of motor customers in the UK actively switched at their last renewal — the highest shopping rate on record.
CONSUMER INTELLIGENCE · 2025
EUROPE(EU27)
€1.41T
Total European insurance premium — the largest consumer-services market on the continent.
INSURANCE EUROPE · 2024
INSIDE THE CHALLENGE
Pricing scrutiny. Aggregator tax. Loyalty penalty.
No other consumer sector has been more reshaped by regulation in the last five years. Pricing-practice rules, consumer-duty, the differential-pricing review and Europe’s insurance-distribution rules have permanently changed the economics of acquisition and renewal. These are the challenges we hear in every scoping call.
Comparison-site dependency
For motor and home, comparison sites now capture the majority of first-click quote traffic, and the commissions keep climbing. Direct-channel margin is squeezed from both sides.
Loyalty-penalty aftermath
Pricing-practice rules and the differential-pricing review forced price equivalence — but left many insurers without a renewal-retention playbook that still works economically.
Protection gap, unconverted
Life, income-protection and critical-illness cover are under-sold across every European market. Interest exists; advised conversion doesn't scale.
Small-business cover under-served
Commercial broker pipelines are thin. Cyber, cargo, professional-indemnity and business-interruption cover are persistently under-penetrated in the small-business segment.
Vulnerable-customer exposure
Conduct rules name vulnerable customers explicitly. A mishandled renewal conversation with a bereaved, ill or elderly customer is now a regulatory-review risk.
OUR FULL ACQUISITION STACK — APPLIED TO HEALTHCARE
Six solutions, one connected engine.
Most partners bring one thing: a search agency, a CRM consultant, or a call centre. We bring all six — designed to interlock, measured to one shared outcome: confirmed, attended, retained patients per pound or euro spent.
Who renews when. And with what intent.
Your policy data, claims history and competitor-rate signals become renewal-timing propensity scores and segment-level opportunity maps, tuned to each market's conduct regime.
- Renewal-window propensity modelling by line & segment
- Lapse-risk early-warning scoring for defence campaigns
- Small-business opportunity mapping by sector & area
- Fair-value & outcomes-grade reporting
The operating system for every renewal conversation.
Telesales, broker partners and service teams see one record — quote to bind to renewal — integrated with your policy-administration, quote-engine and claims systems.
- Sales & Service Hub build for insurance pipelines
- Integration with policy-administration & quote-engine platforms
- Broker & advised-channel partner workflows
- Quote to bind to renewal to retention reporting
Content the compliance team actually approves.
Every asset — renewal notices, explainer videos, business landing pages, advised-channel collateral — is designed around fair-value, consumer-protection and distribution-transparency rules.
- Fair-value-aligned renewal creative & messaging
- Multi-language localisation across markets
- Protection-gap educational content
- Small-business segment storytelling
Inbound pipeline, not comparison-site tax.
Owned funnels that reduce comparison-site dependency and rebuild direct margin — every lead scored, every source traceable, every conversation compliant.
- Direct-quote funnels for motor, home, pet & travel
- Renewal-window-timed outbound list generation
- Advised-protection appointment-setting
- Small-business & cyber pipeline prospecting
Sites that quote, bind, and comply.
The conversion infrastructure that carries your campaigns — quote flows, document libraries, renewal self-service and broker portals, all distribution- and conduct-aligned.
- Product-line microsites & renewal landing pages
- Quote & bind flows with policy-summary delivery
- Self-service renewal & mid-term-adjustment portals
- Broker, introducer & affinity-partner portals
Where strategy meets the renewal.
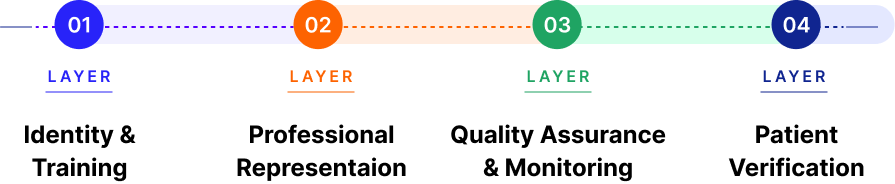
Certified, verified, accountable teams for direct renewal defence, protection advised-sale support and small-business prospecting. Every representative under GoSales Verified™.
- Renewal-retention & save-desk telesales
- Life & protection appointment-setting
- Small-business & commercial field
- Broker-network overflow & affinity-partner support
GoSales Verified™
Brand-safe acquisition, acrossevery regulator.
Healthcare is the most scrutinised consumer sector in Europe for data handling and advertising conduct — the most sensitive class of personal data, medical-advertising codes, medical-device regulation and national medical-advertising standards apply at once. GoSales Verified™ is how we’ve built a commercial operation where every interaction passes all of them.
frequently asked
The questions automotive leaders ask us first.
Drawn from real automotive-sector RFPs and commercial reviews across Ireland, the UK and EU markets.
Insurance telesales has a complaints history. Why will our programme be different?
Because every representative operates under GoSales Verified™ — background-checked, certified, carrying client-branded identification with a code the customer can scan to verify in real time. Every application is independently verified on a recorded call with an immutable audit trail, and the quality threshold is written into the contract as a minimum, not an aspiration.
How do you handle vulnerable customers and fair-value requirements?
Vulnerable-customer protocols are built into scripting, scorecards and verification flows, aligned with conduct and fair-value rules in each market. Representatives are trained to spot bereavement, illness, age, financial-hardship and cognitive signals and to follow escalation paths, including declining to complete a sale.
Can you integrate with our policy-administration, quote-engine and claims systems?
Can you support comparison-site defence as well as direct acquisition?
Can you run across Ireland, the UK and multiple EU markets with different regulators?
Yes. A central programme spine — data, system, reporting, quality framework and training — is adapted locally to each regulator, with one review, one dashboard and one accountable partner rather than a patchwork.
Can you support advised-channel protection as well as direct property and casualty?
Yes — consent-verified life, income-protection and critical-illness appointments feeding your adviser, broker or in-house advised channel, with suitability records intact.
Do you report on policies or just leads?
Policies, and beyond — bind, first-renewal, lapse rate and complaint, reported to a cadence that stands up to fair-value and outcomes monitoring, not vanity dashboards.
How fast can we stand up a programme?
Win the renewal. Defend the book.
Talk to our team about a compliant, data-led insurance acquisition programme across motor, home, life, health or commercial — in Ireland, the UK, or your priority EU markets.